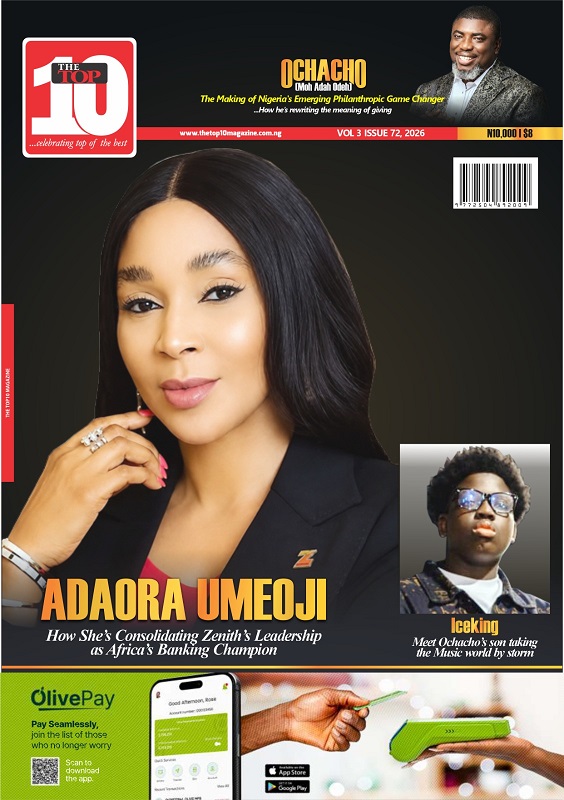
By The Top10 Reporters
How Nigeria’s banking giant strengthened its financial dominance, broke new records, rewarded shareholders and accelerated its march towards becoming a truly Pan-African financial leader
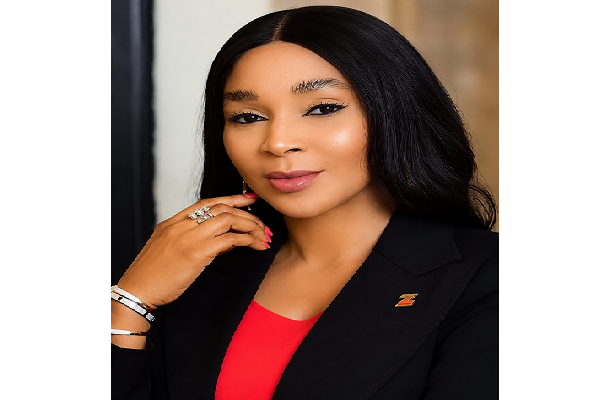
When Dame Dr. Adaora Umeoji, OON, assumed office as Group Managing Director and Chief Executive Officer of Zenith Bank Plc on June 1, 2024, she made history as the first woman to occupy the position in the institution’s history.
But beyond the symbolism of her emergence, her appointment represented something much bigger: the beginning of a new chapter in the story of one of Nigeria’s most formidable financial institutions.
The responsibility was enormous. Zenith Bank had been built over more than three decades into a dominant Nigerian banking franchise with an enviable reputation for profitability, capital strength, technological innovation, corporate governance and service excellence. It was an institution founded by Jim Ovia, CFR, in 1990 and one that had consistently occupied the commanding heights of the Nigerian banking industry.
The question, therefore, was never simply whether Umeoji could become the bank’s first female CEO. It was whether she could sustain and strengthen the formidable legacy she inherited while positioning Zenith for the next phase of competition in an increasingly integrated African and global financial system.
Just over two years into her tenure, the answer is increasingly evident in the numbers, the market, the awards, the expanding geographical footprint and the confidence of shareholders and customers.
Under Umeoji and her management team, Zenith Bank has not merely preserved its position at the top of Nigeria’s banking hierarchy; it has set new benchmarks in profitability, market valuation, capitalisation, shareholder returns, asset quality, digital transformation and international expansion.
The most striking validation came on July 16, 2026, when Zenith Bank was named Africa’s Best Bank at the prestigious Euromoney Awards for Excellence in London. The institution also retained the title of Nigeria’s Best Bank, making it the second consecutive year it won the national category.
For an institution that has spent years building a reputation for excellence, the Euromoney double represents more than another trophy. It is a powerful external endorsement of the bank’s financial strength, strategic execution, risk management, customer proposition and increasingly international character.
A RECORD-BREAKING FINANCIAL PERFORMANCE
The clearest evidence of Zenith Bank’s performance under Umeoji is found in its financial results.
For the 2025 financial year, the bank reported ₦4.19 trillion in gross earnings and ₦1.04 trillion in profit after tax, maintaining its position as Nigeria’s most profitable bank.
The achievement was particularly significant because Zenith became the only Nigerian bank to record consecutive annual profit-after-tax figures above the ₦1 trillion mark in 2024 and 2025.
In 2025, net interest income increased by approximately 53 percent to ₦2.64 trillion, while customer deposits rose to about ₦24.47 trillion. Loans and advances also expanded, supporting key sectors of the Nigerian economy including manufacturing, agriculture, trade and telecommunications.
The performance translated directly into shareholder value.
Zenith doubled its total dividend from ₦5 per share in 2024 to ₦10 per share in 2025, comprising an interim dividend of ₦1.25 and a final dividend of ₦8.75. The payout represents one of the strongest demonstrations of shareholder value creation in the Nigerian banking industry in recent years.
It was not simply a case of growing earnings. Zenith also improved the quality of its loan book.
Its non-performing loan ratio declined from approximately 4.7 percent in 2024 to about 3.8 percent in 2025, reflecting a deliberate effort to strengthen asset quality and clean up legacy exposures.
The result was a financial institution growing its loan book while simultaneously strengthening the quality of its assets—a combination that speaks to disciplined lending and risk management.
THE ₦1 TRILLION PROFIT MILESTONE
One of the defining records of the Umeoji era was Zenith Bank’s crossing of the ₦1 trillion profit-after-tax threshold.
The bank became the first Nigerian bank to record profit after tax above ₦1 trillion in a single financial year.
More remarkable was the ability to repeat the feat.
The bank’s consecutive trillion-naira profit performance in 2024 and 2025 transformed what initially appeared to be a historic milestone into evidence of sustainable earnings capacity.
For Umeoji and her team, the achievement was a product of disciplined execution rather than an isolated windfall. Strong interest income, improved asset deployment, trade finance, foreign exchange activities, transaction banking, digital channels and effective balance-sheet management combined to support the performance.
The bank’s strong position in international trade has also been critical.
Zenith reportedly accounted for 32.31 percent of Nigeria’s NXP transactions in 2025, reinforcing its position as a major facilitator of non-oil export proceeds and cross-border trade.
This is particularly significant at a time when Nigeria is seeking to diversify its economy away from excessive dependence on crude oil.
By supporting exporters, corporates and international trade flows, Zenith is not merely generating income for itself; it is playing an important role in the financial infrastructure required to support Nigeria’s economic diversification.
THE CAPITAL ADVANTAGE
Another major pillar of Zenith Bank’s performance has been capital strength.
In response to the Central Bank of Nigeria’s recapitalisation requirement, Zenith completed a landmark capital-raising exercise that lifted its capital base to more than ₦614 billion, comfortably above the ₦500 billion threshold required for commercial banks with international authorisation.
The capital raise was more than regulatory compliance.
It provided Zenith with a stronger platform from which to finance large-scale infrastructure, manufacturing, agriculture, energy, trade and other long-term projects.
At the end of 2025, the bank’s Capital Adequacy Ratio stood at approximately 25 percent, while its liquidity ratio was about 71 percent, both comfortably above regulatory requirements.
For investors and rating agencies, the depth of the capital buffer provides an important source of confidence.
It gives Zenith room to absorb shocks, support credit growth and finance its expanding international ambitions without placing undue pressure on its balance sheet.
THE FIRST NIGERIAN BANK TO CROSS ₦5 TRILLION MARKET CAPITALISATION
Perhaps no market milestone captures investor confidence in Zenith Bank more dramatically than its record-breaking market valuation.
In 2026, Zenith became the first Nigerian bank to surpass ₦5 trillion in market capitalisation.
The milestone came amid a sustained rally in the bank’s shares, driven by strong financial results, investor confidence and optimism surrounding its international expansion and planned London Stock Exchange strategy.
At various points in 2026, Zenith’s market capitalisation climbed beyond ₦5 trillion and reached levels above ₦5.4 trillion, reinforcing its status as Nigeria’s most valuable banking institution by market value.
The significance of the achievement goes beyond the headline number.
Market capitalisation represents the collective valuation investors place on an institution’s future earnings, resilience, governance and growth prospects. Zenith’s performance therefore indicates that the market is increasingly pricing the bank not simply as Nigeria’s largest bank by Tier-1 capital, but as a financial institution with substantial continental and international potential.
17 CONSECUTIVE YEARS AT THE TOP
While the ₦5 trillion milestone is new, Zenith’s leadership in capital strength is anything but.
The bank retained its position as Nigeria’s No. 1 bank by Tier-1 Capital for the 17th consecutive year, according to The Banker’s Top 1000 World Banks ranking.
That 17-year streak is one of the strongest indicators of the consistency of Zenith’s capital management.
It means that while the Nigerian banking industry has undergone dramatic changes, mergers, acquisitions, regulatory reforms and technological disruption, Zenith has remained at the top of the Tier-1 capital rankings for nearly two decades.
The achievement also demonstrates the strength of the institution Umeoji inherited—and the importance of her administration’s responsibility to preserve and expand that advantage.
A BANK THAT IS GETTING BIGGER, BUT ALSO CLEANER
One of the more significant features of Zenith’s latest performance is the relationship between growth and risk management.
In the first quarter of 2026, total assets stood at about ₦32.01 trillion, while customer deposits rose year-on-year to approximately ₦24.47 trillion.
Gross loans and advances increased to about ₦12.04 trillion, while net loans rose to approximately ₦11.38 trillion.
Yet the bank’s non-performing loan ratio remained around 3.79 percent, compared with 4.70 percent at the end of 2024.
This is an important distinction.
Growth in banking is only valuable when it is supported by asset quality. Zenith’s ability to grow lending while reducing the proportion of impaired loans demonstrates the effectiveness of its credit discipline and risk management architecture.
The bank’s loan-loss coverage ratio was also reported at about 172.6 percent for 2025, providing a significant buffer against impaired exposures.
A MORE DIVERSIFIED REVENUE ENGINE
Another important dimension of Zenith’s recent performance has been the diversification of its income sources.
In the first quarter of 2026, gross earnings rose to approximately ₦1.01 trillion, while net interest income increased to about ₦634.1 billion.
More striking was the performance of net fee and commission income, which rose by 44.6 percent year-on-year to approximately ₦81 billion.
The figure points to a bank increasingly monetising transaction banking, digital platforms, cards, trade services and other fee-generating businesses.
For Zenith, this diversification is strategically important because it reduces excessive reliance on interest-rate movements and strengthens the bank’s capacity to generate recurring transaction-based income.
THE DIGITAL ZENITH
For an institution operating in a financial environment increasingly dominated by technology, Zenith’s digital transformation agenda has become one of the most important components of its competitiveness.
The bank has historically been regarded as one of the pioneers of digital banking in Nigeria, and under Umeoji that tradition has accelerated.
A major core banking upgrade undertaken during her tenure was designed to improve scalability, speed and customer experience.
The bank has also expanded its digital channels, strengthened cybersecurity and improved data analytics capabilities.
Its internet banking platform has been enhanced with a redesigned interface and broader functionalities, including cross-border intra-African transfers, treasury bill investments and payment of government levies.
The eaZy by Zenith digital wallet is another component of the bank’s evolving digital ecosystem.
For retail customers, digital transformation is not simply about technology. It is about reducing friction, improving accessibility, making transactions faster and extending financial services to people beyond traditional banking halls.
Zenith has also expanded agency banking, through which it has reached more than four million customers, particularly in underserved communities.
THE RETAIL AND SME FRONT
Umeoji’s leadership has also placed considerable emphasis on retail and small and medium-sized businesses.
The bank sees SMEs as critical to Nigeria’s economic future, particularly because of their contribution to employment, entrepreneurship and economic activity.
Zenith has developed financing solutions including cash-flow-based finance, asset and equipment finance, cooperative lending and the Z-Woman loan, designed to support women-led businesses.
The bank’s retail business has also grown considerably.
Of the approximately ₦24 trillion in customer deposits in 2025, retail deposits accounted for roughly ₦4.9 trillion. The bank disbursed nearly 3,000 retail loans valued at approximately ₦89.5 billion during the period.
These figures underline the importance of retail and SME banking to Zenith’s next phase of growth.
FROM NIGERIAN CHAMPION TO PAN-AFRICAN POWERHOUSE
Perhaps the most ambitious aspect of the Umeoji era is the speed with which Zenith has moved to transform its international footprint.
The strategy is not simply about opening branches in more countries. It is built around trade flows, corporate relationships, payments, remittances, structured transactions and the increasing integration of African economies.
In 2026, Zenith strengthened its presence in three strategically important directions.
Côte d’Ivoire: Gateway to Francophone Africa
Zenith formally launched its Côte d’Ivoire subsidiary in Abidjan in April 2026.
The move gives the bank a strategic foothold in the Francophone West African market and access to the broader WAEMU economic bloc.
Abidjan’s status as a major commercial and financial centre makes it a natural base from which Zenith can support corporate banking, trade finance, payments and cross-border transactions.
Kenya: The East African Gateway
In April 2026, Zenith completed the acquisition of 100 percent of Paramount Bank Kenya Limited, following regulatory approvals.
The transaction gives Zenith an immediate presence in Kenya, one of East Africa’s largest and most sophisticated economies.
The acquisition also provides access to an established banking infrastructure, customer base, local expertise and seven branches.
The strategy is significant because Kenya offers Zenith a platform from which it can build deeper relationships across East Africa.
France and the United Kingdom
Zenith’s international ambitions also include Europe.
The bank has established a presence in Paris, France, while strengthening its operations in the United Kingdom, including Manchester.
The next major ambition could be even bigger: a proposed London Stock Exchange listing in 2027.
If realised, the listing would potentially provide Zenith with access to international capital markets while strengthening its visibility among global investors and clients.
The objective is consistent with the broader vision of transforming Zenith from a Nigerian banking giant into a truly global African financial brand.
THE HUMAN CAPITAL DIMENSION
Behind every balance sheet is a workforce.
One of the less frequently discussed dimensions of Umeoji’s leadership has been her emphasis on people and staff welfare.
The materials surrounding her tenure indicate extensive staff promotions, with about 80 percent of employees reportedly promoted over the two-year period, including non-professional staff.
Earlier in her tenure, about 50 percent of the workforce was reported to have been promoted in the first year.
There was also a major salary review.
The underlying philosophy is clear: an institution cannot sustain excellence without motivated people.
For Umeoji, employee advancement is not simply a reward mechanism. It is part of building an institution with strong succession pipelines and a workforce capable of taking Zenith into its next phase.
Her own philosophy on leadership captures this approach.
As the first woman to lead Zenith, she has emphasised that being a pioneer carries an obligation to build opportunities for others while ensuring that merit and institutional excellence remain paramount.
THE TEAM BEHIND THE NUMBERS
Although Umeoji occupies the most visible leadership position, Zenith’s performance is the product of a broader management architecture made up of experienced professionals with deep institutional knowledge.
Among them is Mrs. Adobi Stella Nwapa, an Executive Director and one of Zenith’s pioneer employees. Having joined the bank in 1990 as its pioneer Customer Service Officer, she brings more than three decades of institutional experience to the executive leadership.
Mr. Anthony Akindele Ogunranti, another senior executive, brings more than 30 years of banking experience spanning corporate, commercial, retail and public-sector banking. He has also played a major role in technology and digital transformation.
Mr. Adamu Saliu Lawani, a seasoned chartered accountant with more than three decades of banking experience, adds substantial financial and accounting expertise to the management structure.
Mr. Louis Odom brings more than two decades of multisectoral banking experience across consumer banking, oil and gas, public-sector, retail and commercial banking.
Mr. Kennedy Onuwa Okwudili, appointed Executive Director effective May 1, 2026, brings extensive accounting and management expertise.
Supporting the executive leadership are other key professionals, including Mr. Felix Egbon, Chief Risk Officer and Group Head of Risk Management; and Mr. Michael Osilama Otu, Company Secretary and Legal Adviser, who has been with Zenith since 1997.
Collectively, the team represents a blend of institutional memory, technical expertise, risk management, corporate banking, technology, legal and financial competence.
That combination is important because Zenith’s current strategy requires much more than a strong CEO. It requires a management structure capable of executing a complex agenda across Nigeria, Africa and international markets.
THE TROPHY CABINET GETS BIGGER
The financial performance has been accompanied by an impressive collection of national and international recognitions.
In 2026 alone, Zenith’s honours include:
• Africa’s Best Bank – Euromoney Awards for Excellence
• Nigeria’s Best Bank – Euromoney Awards for Excellence
• Best Bank in Nigeria – Global Finance
• Best Commercial Bank – World Finance
• Best Corporate Governance – World Finance
• Biggest Bank in Nigeria by Tier-1 Capital – The Banker
• Best FX Provider – Global Finance
• Sustainable Bank of the Year, Nigeria – International Banker
• Best Customer Service Provider in Africa – International Banker
The bank’s achievements in 2025 were equally impressive, with recognitions from Global Finance, World Finance, Euromoney, The Banker, International Banker, BusinessDay and other respected institutions.
Its sustainability and corporate responsibility efforts have also attracted recognition, including honours at the SERAS Awards for responsible business, transparency and reporting, gender equality and women empowerment.
A LEADER WHO HAS ALSO BECOME AN AWARD-WINNING FIGURE
The recognition has not been limited to Zenith Bank as an institution.
Umeoji herself has emerged as one of Nigeria’s most recognised banking executives.
Among her honours are Bank CEO of the Year recognition from Champion Newspaper, Banker of the Year recognition from Leadership Newspaper, subsequent Banker of the Year recognition from New Telegraph and Champion Newspaper, and inclusion among 50 Women Making Impact by Arise News.
Her professional preparation is equally notable.
Her academic background spans sociology, accounting and law, complemented by executive management education from institutions including Harvard Business School, Wharton School, MIT Sloan School of Management and Columbia Business School.
But perhaps the most important part of her professional story is that she is not an outsider brought in to lead Zenith.
She is a product of the institution.
With nearly three decades of banking experience and more than two decades at Zenith, she represents institutional continuity while simultaneously embodying a new generation of leadership.
BEYOND BANKING: SPORTS, SOCIETY AND RESPONSIBILITY
Zenith’s corporate citizenship has remained an important component of its identity.
The bank continues to support initiatives in education, healthcare, security, sports and community development.
In sports, Zenith has maintained a particularly strong relationship with women’s basketball, serving as the sole sponsor of the annual national women’s basketball league.
It also sponsors competitions such as the Delta State Principals Cup and Headmasters Cup.
These initiatives reinforce the institution’s belief that the responsibilities of a major corporation extend beyond its balance sheet.
Its sustainability framework also integrates environmental and social considerations into project financing and risk management.
The bank reported that approximately 94 percent of new and existing transactions were assessed for environmental and social risks in 2025, while 95 percent of financed projects were actively monitored.
WHY THE ZENITH STORY MATTERS
The most compelling feature of Zenith Bank’s current story is not one isolated achievement.
It is the combination.
A bank that has remained Nigeria’s No. 1 by Tier-1 capital for 17 consecutive years has now become the first Nigerian bank to cross ₦5 trillion in market capitalisation.
A bank that has built a reputation for strong profitability has now delivered consecutive trillion-naira profit-after-tax results.
A bank that has historically been identified with Nigerian banking is now building strategically across Francophone West Africa, East Africa and Europe.
A bank known for technological innovation is accelerating digital transformation at a time when customer expectations are being radically reshaped by fintech and artificial intelligence.
And a bank that has historically rewarded shareholders is now delivering a doubled dividend payout while investing aggressively in capital, people and international expansion.
This is what makes the Adaora Umeoji era particularly significant.
THE ADAORA Umeoji EFFECT: FROM SUCCESSION TO TRANSFORMATION
Umeoji inherited a powerful institution.
Her challenge was not to rescue a struggling bank, but to lead a successful institution into a more demanding future.
That distinction matters.
The performance of Zenith Bank under her leadership suggests a strategy built around four interconnected priorities: financial strength, digital innovation, human capital and global expansion.
Financial strength provides the foundation.
Digital innovation improves competitiveness.
Human capital ensures institutional continuity.
International expansion creates the next frontier of growth.
The result is an institution that is increasingly positioning itself beyond the traditional definition of a Nigerian bank.
The transformation is also closely connected to the founding vision of Jim Ovia, whose ambition has always extended beyond Nigeria.
The expansion into Côte d’Ivoire and Kenya, alongside the existing operations in the United Kingdom, France, Ghana, Sierra Leone, The Gambia, the UAE and representative presence in China, indicates that the Zenith brand is becoming increasingly continental and international.
THE ROAD AHEAD
The next phase will be more demanding.
Competition across African banking is becoming increasingly intense. Regulatory requirements are rising. Technology is transforming customer behaviour. Cybersecurity threats are growing. Global economic conditions remain uncertain. And African banks seeking international relevance must compete against institutions with much larger capital bases.
For Zenith, the answer appears to lie in its capital strength, technology, customer franchise, risk management culture and ability to leverage its Nigerian foundation to facilitate African trade and investment.
The planned London Stock Exchange listing, if achieved, could become another defining chapter.
The expansion into Kenya and Côte d’Ivoire could also provide a platform for deeper penetration into the East African, Francophone West African and broader African markets.
The challenge will be to replicate the Zenith model without losing the discipline that made it successful in Nigeria.
THE VERDICT: A NEW CHAPTER IN ZENITH’S STORY
Three and a half decades after Jim Ovia founded Zenith Bank, the institution stands at another defining moment.
Its financial strength is evident.
Its capital position is formidable.
Its profitability remains exceptional.
Its shareholder returns have increased.
Its asset quality has improved.
Its digital capabilities continue to expand.
Its workforce is being repositioned for the future.
Its international footprint is growing.
And its awards cabinet continues to fill.
The crowning recognition so far in 2026—Africa’s Best Bank at the Euromoney Awards for Excellence—provides a fitting summary of how far Zenith has travelled.
For Adaora Umeoji, however, the real test lies beyond the trophies.
It lies in whether Zenith can convert its current strength into sustainable long-term value; whether its African expansion can produce meaningful economic impact; whether its digital transformation can deepen financial inclusion; whether its capital can finance productive businesses; and whether the institution can continue to build a culture in which excellence survives individual personalities.
On the evidence of the past two years, the signs are encouraging.
Adaora Umeoji’s tenure is already historic because she became Zenith Bank’s first female CEO.
But the more enduring significance of her leadership may ultimately be measured by something more substantial than being the first woman to occupy the office.
It may be remembered as the period when Zenith Bank moved decisively from being Nigeria’s banking champion to an increasingly formidable African financial leader.
That is the real story behind the numbers, the records and the trophies.
And that is why, in the continuing story of Zenith Bank, the Adaora Umeoji chapter is proving to be not merely a story of succession—but a story of renewal, acceleration and transformation.